 Freedom Calcs
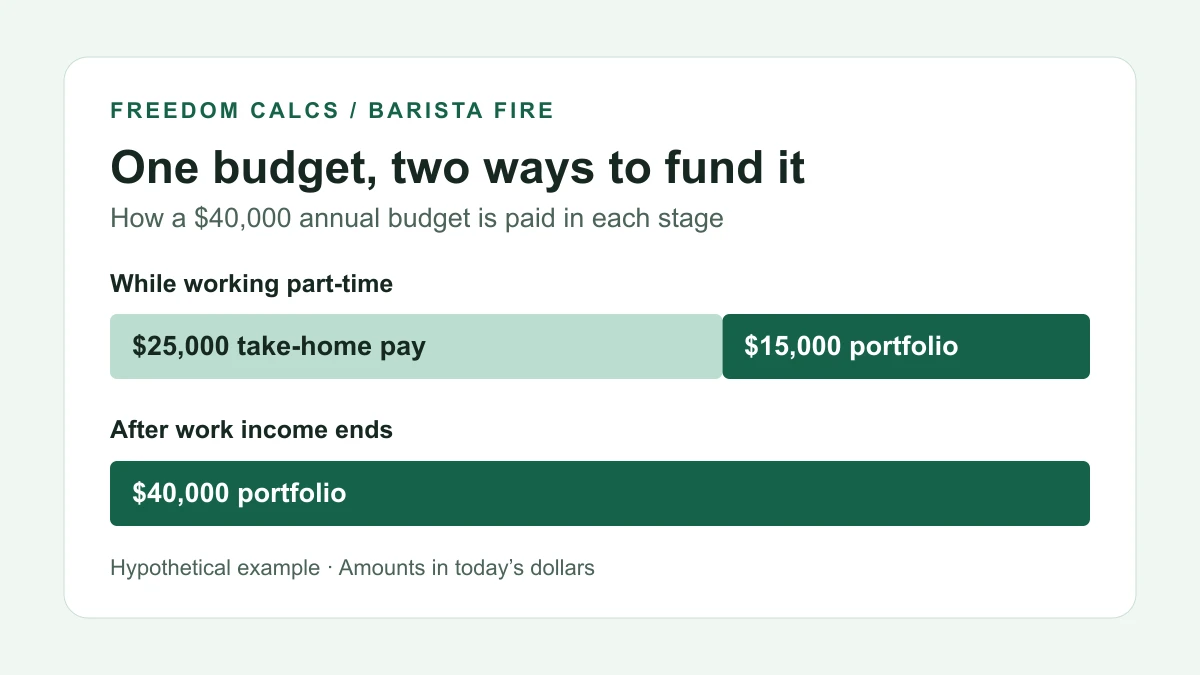
Barista FIRE Meaning: What It Is and How to Plan It
Barista FIRE means covering part of your expenses with part-time work while your portfolio funds the rest. See the meaning, the math, and how it differs from Coast FIRE.
A clearer path to retirement
Estimate the investments needed today to grow toward retirement.
Invested assets needed today
$263,555
You haven’t reached your Coast target yet.
Smooth lines reflect constant assumptions, not market forecasts. Contributions continue to retirement on the “keep” path.
With $1,000 invested each month, you could reach Coast FIRE at age 49 + 4 months under these assumptions. Stopping contributions today projects $379,428 at age 65. All amounts are in today’s dollars.
| Age | Keep contributing | Stop now | Coast threshold |
|---|---|---|---|
| Age 30 | $100,000 | $100,000 | $263,555 |
| Age 31 | $116,096 | $103,883 | $273,790 |
| Age 32 | $132,816 | $107,918 | $284,422 |
| Age 33 | $150,186 | $112,109 | $295,468 |
| Age 34 | $168,231 | $116,463 | $306,942 |
| Age 35 | $186,976 | $120,985 | $318,862 |
| Age 36 | $206,450 | $125,684 | $331,245 |
| Age 37 | $226,679 | $130,565 | $344,109 |
| Age 38 | $247,694 | $135,635 | $357,473 |
| Age 39 | $269,526 | $140,903 | $371,355 |
| Age 40 | $292,205 | $146,375 | $385,777 |
| Age 41 | $315,765 | $152,059 | $400,758 |
| Age 42 | $340,240 | $157,964 | $416,322 |
| Age 43 | $365,665 | $164,099 | $432,490 |
| Age 44 | $392,078 | $170,471 | $449,285 |
| Age 45 | $419,516 | $177,092 | $466,733 |
| Age 46 | $448,020 | $183,969 | $484,859 |
| Age 47 | $477,631 | $191,114 | $503,689 |
| Age 48 | $508,392 | $198,535 | $523,249 |
| Age 49 | $540,347 | $206,246 | $543,570 |
| Age 49 + 4 months | $551,273 | $208,882 | $550,517 |
| Age 50 | $573,544 | $214,255 | $564,679 |
| Age 51 | $608,030 | $222,576 | $586,608 |
| Age 52 | $643,855 | $231,219 | $609,389 |
| Age 53 | $681,071 | $240,199 | $633,055 |
| Age 54 | $719,732 | $249,527 | $657,640 |
| Age 55 | $759,895 | $259,217 | $683,179 |
| Age 56 | $801,618 | $269,284 | $709,710 |
| Age 57 | $844,961 | $279,742 | $737,272 |
| Age 58 | $889,987 | $290,605 | $765,904 |
| Age 59 | $936,761 | $301,891 | $795,647 |
| Age 60 | $985,353 | $313,615 | $826,546 |
| Age 61 | $1,035,831 | $325,794 | $858,645 |
| Age 62 | $1,088,269 | $338,446 | $891,991 |
| Age 63 | $1,142,744 | $351,590 | $926,631 |
| Age 64 | $1,199,335 | $365,244 | $962,617 |
| Age 65 | $1,258,123 | $379,428 | $1,000,000 |
Compare three paths. Each contribution continues through your retirement age, even after the Coast milestone.
| Contribution plan | Monthly amount | First Coast milestone | Assets at retirement |
|---|---|---|---|
| Keep contributing | $1,000.00 | Age 49 + 4 months | $1,258,123 |
| Contribute half | $500.00 | Not reached before retirement | $818,776 |
| Stop now | $0.00 | Not reached before retirement | $379,428 |
These are alternative assumptions, not probabilities or confidence intervals. Spending, inflation, and contributions stay the same.
| Nominal return | Coast target today | Retirement assets, keep contributing |
|---|---|---|
| 6% | $366,098 | $996,006 |
| 7% | $263,555 | $1,258,123 |
| 8% | $190,314 | $1,600,350 |
Coast FIRE means investments could reach your retirement target without further contributions.
Also called Coast FI. Fund living costs separately.
A Coast FI number calculator discounts your retirement target by expected growth.
Coast number = ($40,000 ÷ 0.04) ÷ (1.07 ÷ 1.03)35 ≈ $263,555
From age 30 to 65, assume 7% nominal growth and 3% inflation. The $1 million target and Coast number are in today’s dollars.
On the Coast FIRE chart, the contributing path reaches Coast when it meets the rising threshold. “Stop now” shows growth without deposits. Cover living costs separately.
Retirement target = spending ÷ withdrawal rate
See the 4 percent benchmark and what to test.
Real return = (1 + return) ÷ (1 + inflation) − 1
Coast target = retirement target ÷ (1 + real return)years
Month-end deposit formula · Federal Reserve Bank of St. Louis on real returns
Retirement at 65, $40,000 spending, 7% return, 3% inflation, 4% withdrawals; today’s USD.
| Current age | Years to retirement | Coast target today | Retirement target |
|---|---|---|---|
| 25 | 40 | $217,840 | $1,000,000 |
| 35 | 30 | $318,862 | $1,000,000 |
| 45 | 20 | $466,733 | $1,000,000 |
Use this Coast FIRE calculator for couples by combining investable balances and using one household budget and retirement date. Two partners, both 40, each have $250,000 invested and plan to retire at 65 on $72,000 a year.
To use the Coast FIRE calculator with pension income, subtract the spendable annual pension from your budget if payments start at retirement. A $24,000 inflation-adjusted pension leaves $48,000 for investments to cover. Enter $48,000 in spending and $500,000 in assets. At 4% withdrawals, 7% nominal growth, and 3% inflation, the retirement target is $1.2 million and today’s Coast target is $462,932, versus $694,398 without the pension.
This coast retirement calculator uses today’s dollars. Test different retirement dates separately. For a pension that starts later, model withdrawals through the income gap.
Compare models: FIRE calculator FAQs.
Both names, including coasting calculator, describe the same model.
Include retirement investments. Exclude emergency funds, near-term spending money, and home equity.
Try less favorable assumptions than the example 7% return and 3% inflation. Constant growth omits market risk.
Historical results cannot guarantee future outcomes.
Assets and the threshold grow at the same rate, preserving any gap.
You meet the modeled threshold. You still need to cover living costs and manage investment risk.
Yes. Equal ages leave no growth period. Negative real returns erode purchasing power.
Enter spending after other income. The model excludes taxes, fees, debt, lifespan, volatility, and retirement withdrawals.
Inputs reset on reload. Our code omits financial values from Google Analytics and AdSense requests. Privacy details.
Bengen’s 1994 research and Cooley, Hubbard, and Walz’s 1998 study tested historical withdrawals.
Budget data from Census ACS rents (2024) and BLS household spending (2023–24). See areas, calculations and limits.
By Freedom Calcs team. Formulas and sources · Corrections.
Published · Updated . Arithmetic checked. No professional financial review.
From the blog
Barista FIRE means covering part of your expenses with part-time work while your portfolio funds the rest. See the meaning, the math, and how it differs from Coast FIRE.
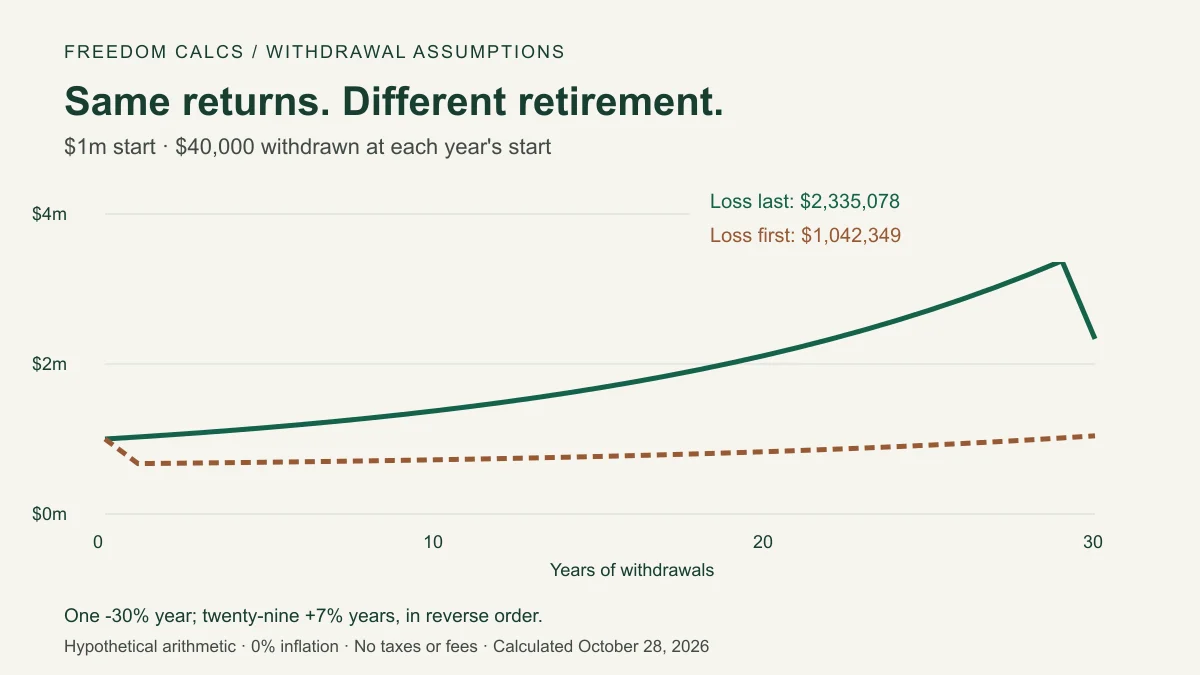
Check the 4% rule's assumptions about time, portfolios, inflation, fees and US history, with reproducible examples of sequence risk and a nine-point checklist.
The 4 percent rule starts with 4% of your portfolio and adjusts that dollar amount for inflation. Compare starting rates and see when a 4% withdrawal plan can run short.